Read Time:2 Minute, 42 Second
THE country has more at stake economically in its trade relationship with China than Beijing does, several groups warned, urging the government to rein in public exchanges that could further strain bilateral ties.
In a joint appeal released Monday, 22 business, labor and other sectoral organizations pointed to the Philippines’s reliance on China and Hong Kong, which they said account for nearly 30 percent of the country’s international trade.
This is compared with the Philippines’s contribution of only 0.3 percent to 0.5 percent of China’s total global trade.
Citing Philippine Statistics Authority (PSA) data for the first half of 2026, the groups said China and Hong Kong accounted for 26.3 percent of Philippine exports and between 27 percent and 29.5 percent of imports in recent years.
“Because trade with China represents a far greater share of Philippine external trade than the Philippine market represents of China’s global trade, we must practice careful economic statecraft while pursuing strategic diversification, stronger domestic industries, local assembly and manufacturing, and sound diplomacy,” the statement said.
Strained relations, they warned, could affect industries that depend on Chinese supplies, including manufacturing, construction, agriculture, energy and retail.
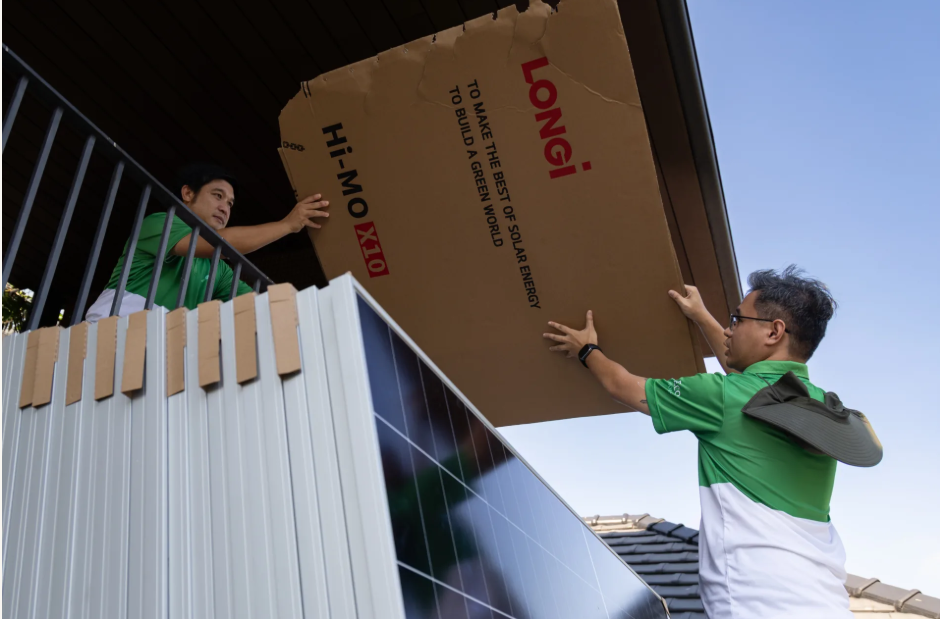
China supplies the Philippines with industrial inputs, machinery, electronics and strategic raw materials, as well as technologies used in renewable energy, electric vehicles and solar power, they said.
Any disruption to these supply links, they added, could raise business costs, affect employment and make essential goods more expensive for consumers.
The groups also cited the country’s dependence on Chinese imports for components and equipment needed in the country’s clean-energy transition.
Leading the signatory groups were: the Philippine Chamber of Commerce and Industry (PCCI), Federation of Philippine Industries (FPI), Employers Confederation of the Philippines (Ecop), Philippine Exporters Confederation (Philexport), and Semiconductor and Electronics Industries in the Philippines (Seipi).
The appeal comes amid heightened exchanges between Chinese Embassy officials and Philippine government officials over bilateral issues, including maritime disputes.
The signatories called on both sides to avoid inflammatory rhetoric, personal exchanges and social media statements that could further escalate tensions.
The groups urged Manila to pursue what they described as a more measured and coordinated foreign policy, with official positions communicated through designated authorities and established diplomatic channels.
For them, defending Philippine sovereignty and maintaining economic cooperation with China need not be mutually exclusive.
Continued dialogue and practical cooperation in trade, investment, tourism, energy security and electric mobility are being called for, alongside efforts to expand the country’s trading relationships and develop domestic manufacturing capacity.
The statement also cited the economic contribution of overseas Filipino workers in China, Hong Kong and Macao, whose remittances support household consumption and spending on education, housing, health care and small businesses.
The signatories said the government should prioritize market access, resilient supply chains, technology transfer, local production and investments that create jobs.
They also urged the Philippines to attract a larger share of regional tourism, investment and business travel by maintaining a predictable environment for businesses.
“Constructive relations with China do not require abandoning Philippine sovereignty, overlooking legitimate concerns, or compromising an independent foreign policy,” the statement said.
“Effective diplomacy means defending national interests while avoiding unnecessary escalation.”
Reprinted from BusinessMirror


Happy
0 %

Sad
0 %

Excited
0 %

Sleepy
0 %

Angry
0 %

Surprise
0 %
 0
 0